

Solutions
Southeast Asia M&A in 3Q2026: Fewer Deals, Bigger Cheques and Capital Staying in the Region
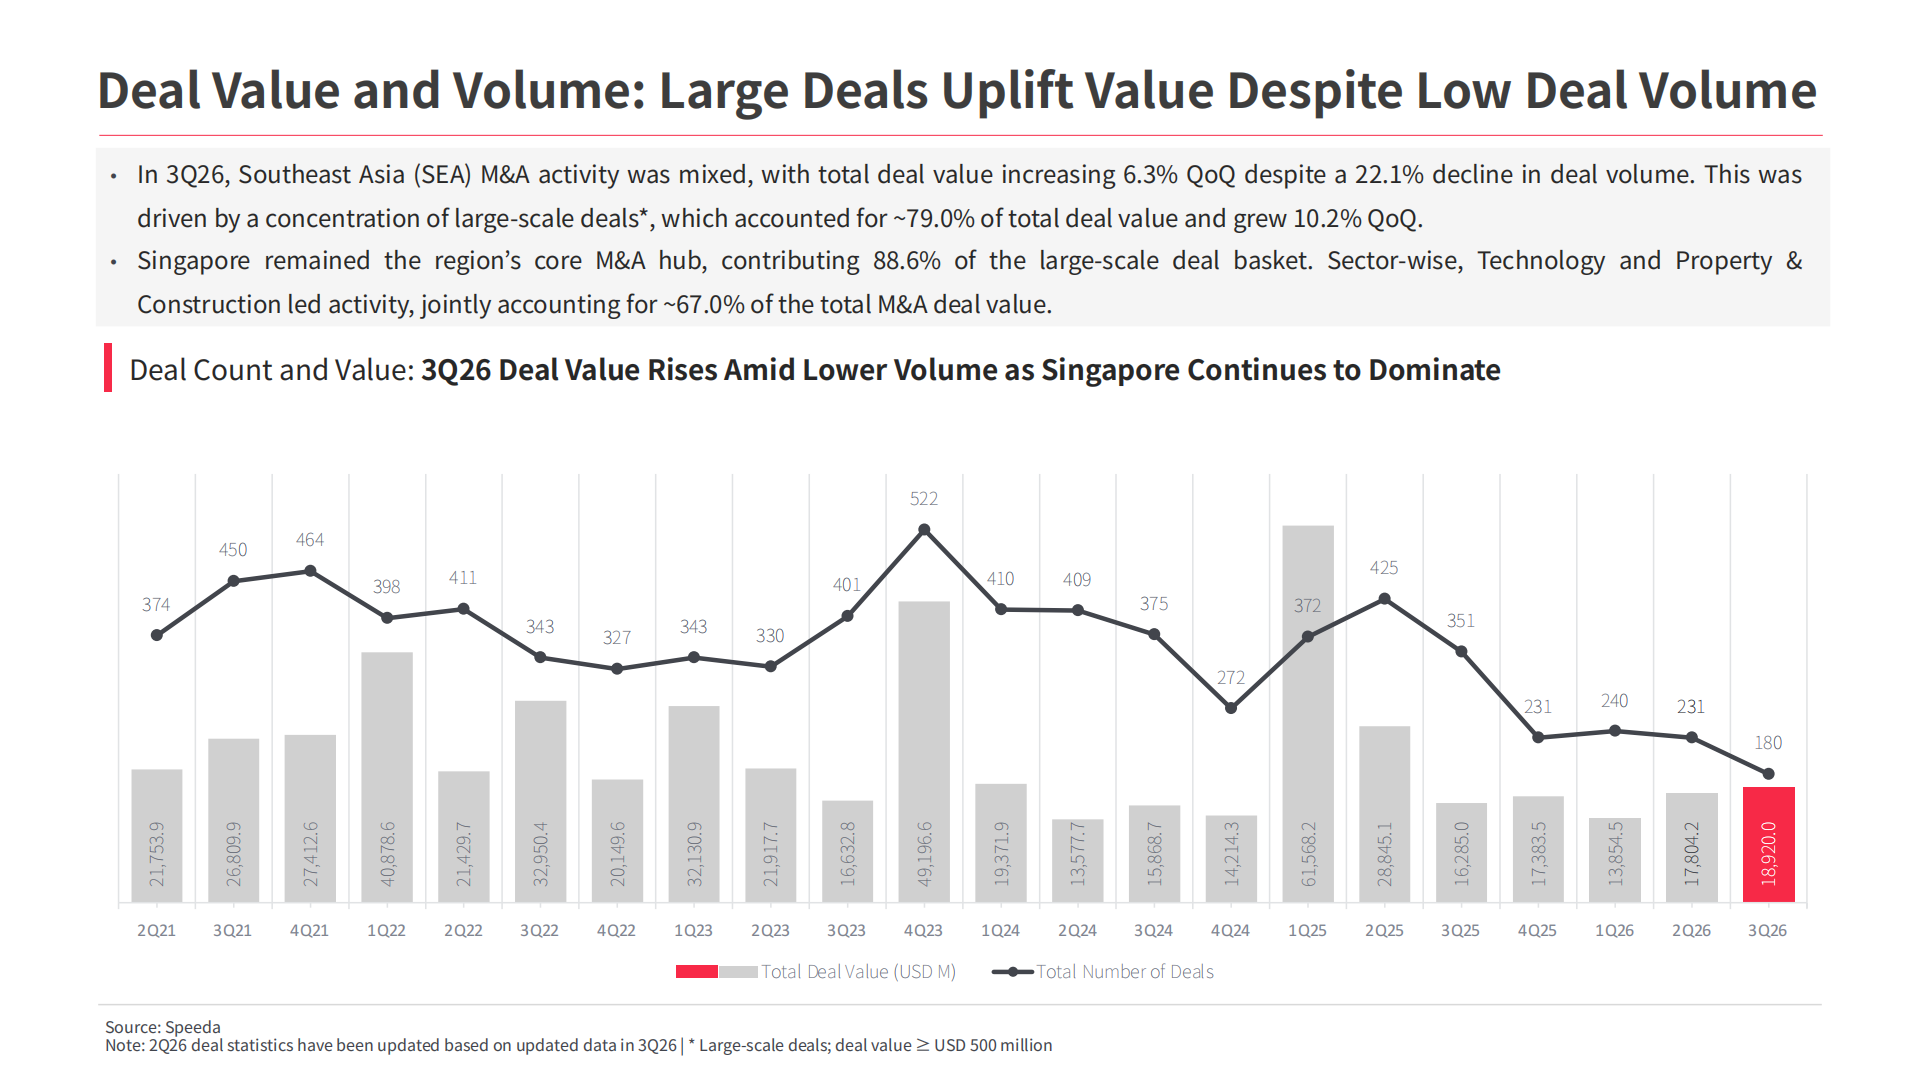
Southeast Asia’s M&A market in 3Q2026 was defined by concentration. Total deal value rose 6.3% QoQ to approximately USD 18.9 billion, while deal volume fell 22.1% to 180 transactions, the lowest quarterly count in Speeda’s tracking since 2Q2021.
Behind that headline are three shifts that matter for PE and VC investors: a small number of large transactions carried the quarter, capital stayed inside the region rather than flowing out, and the funding mix for startups moved further away from private equity.
A handful of large transactions drove the quarter
Transactions valued at USD 500 million or more accounted for approximately 79% of total deal value, and their combined value grew 10.2% QoQ. Singapore was at the centre of this, accounting for approximately 75.5% of total SEA M&A deal value.
The largest transactions of the quarter were:
- KKR and Singtel’s acquisition of the remaining stake in ST Telemedia Global Data Centres (~USD 5.2 billion)
- CapitaLand Integrated Commercial Trust’s acquisition of Paragon on Orchard Road (~USD 3.0 billion)
- The buyback of Manus AI from Meta by its original investors and private equity firms (~USD 2.0 billion)
At the sector level, Technology and Property & Construction together accounted for roughly 67% of total deal value, with each reaching nearly six times its 2Q2026 level. Capital went to assets with stable, long-term demand: AI-ready digital infrastructure and prime real estate.
The implication for investors: with fewer transactions taking place, each large deal sets the benchmark for pricing and buyer appetite in its sector. Tracking these deals closely matters more than following aggregate volume.
What the full report adds: the complete Top 10 SEA M&A deals with target and buyer details, deal value by sector and country, and the leading financial and legal advisors.
Capital stayed inside the region
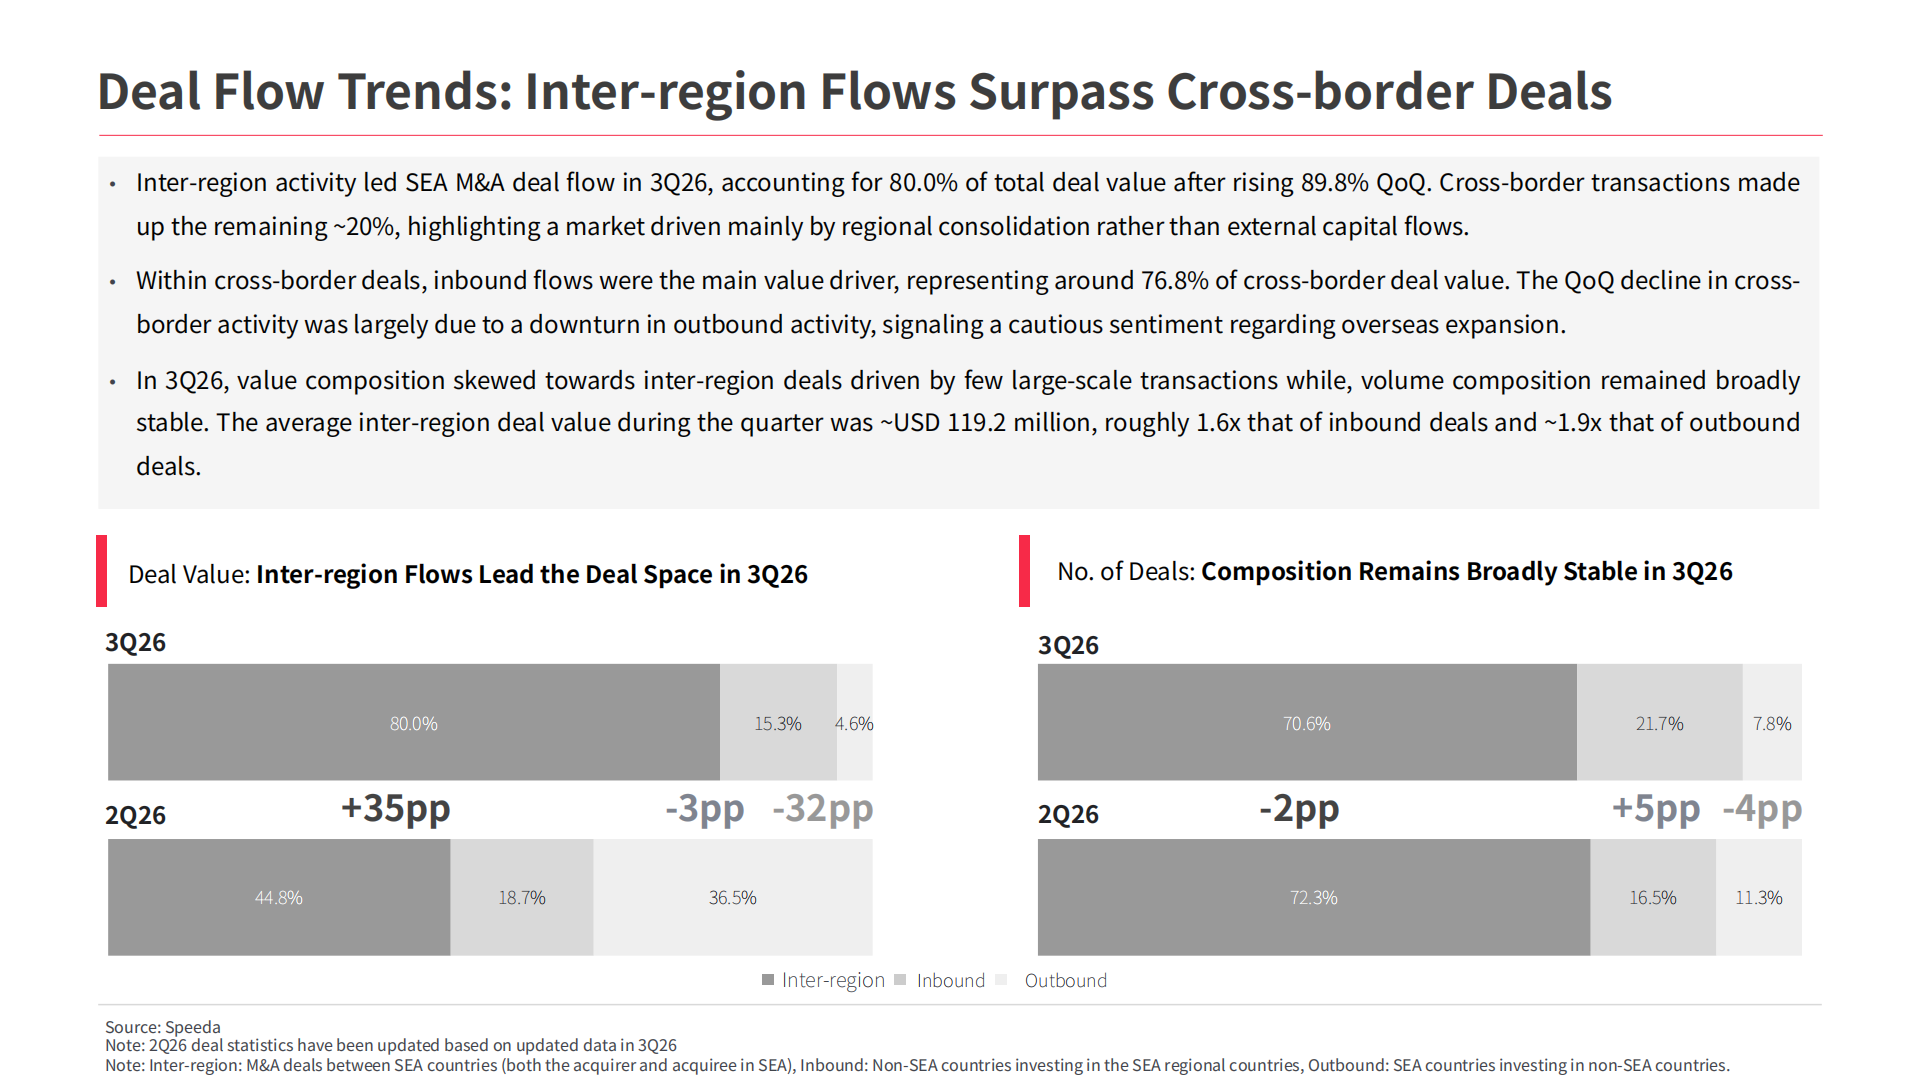
Inter-region transactions, where both buyer and target are in Southeast Asia, accounted for 80.0% of total deal value in 3Q2026, up from 44.8% in 2Q2026. Cross-border deals made up the remaining 20%.
The sharpest change came from outbound activity. Outbound deals fell to 4.6% of deal value from 36.5% in the previous quarter, which points to caution among Southeast Asian buyers about expanding overseas. Within cross-border deals, inbound flows were the main driver, at around 76.8% of cross-border value.
Deal size also differed by direction. The average inter-region transaction was approximately USD 119.2 million, roughly 1.6 times the average inbound deal and 1.9 times the average outbound deal. Meanwhile, the share of deals by count stayed broadly stable QoQ.
Malaysia illustrates the regional consolidation theme. Malayan Banking’s acquisition of the remaining stake in Maybank Ageas Holdings (~USD 1.19 billion) helped Malaysia account for around 94% of SEA finance and banking deal value.
The implication for investors: when regional strategic buyers are the most active and write the largest cheques, they become an increasingly important exit route. Understanding who those buyers are, and what they are acquiring, is central to exit planning.
What the full report adds: a detailed breakdown of inter-region, inbound and outbound flows by value and volume, country-level deal activity, and the transactions behind them.
Startup funding moved away from private equity
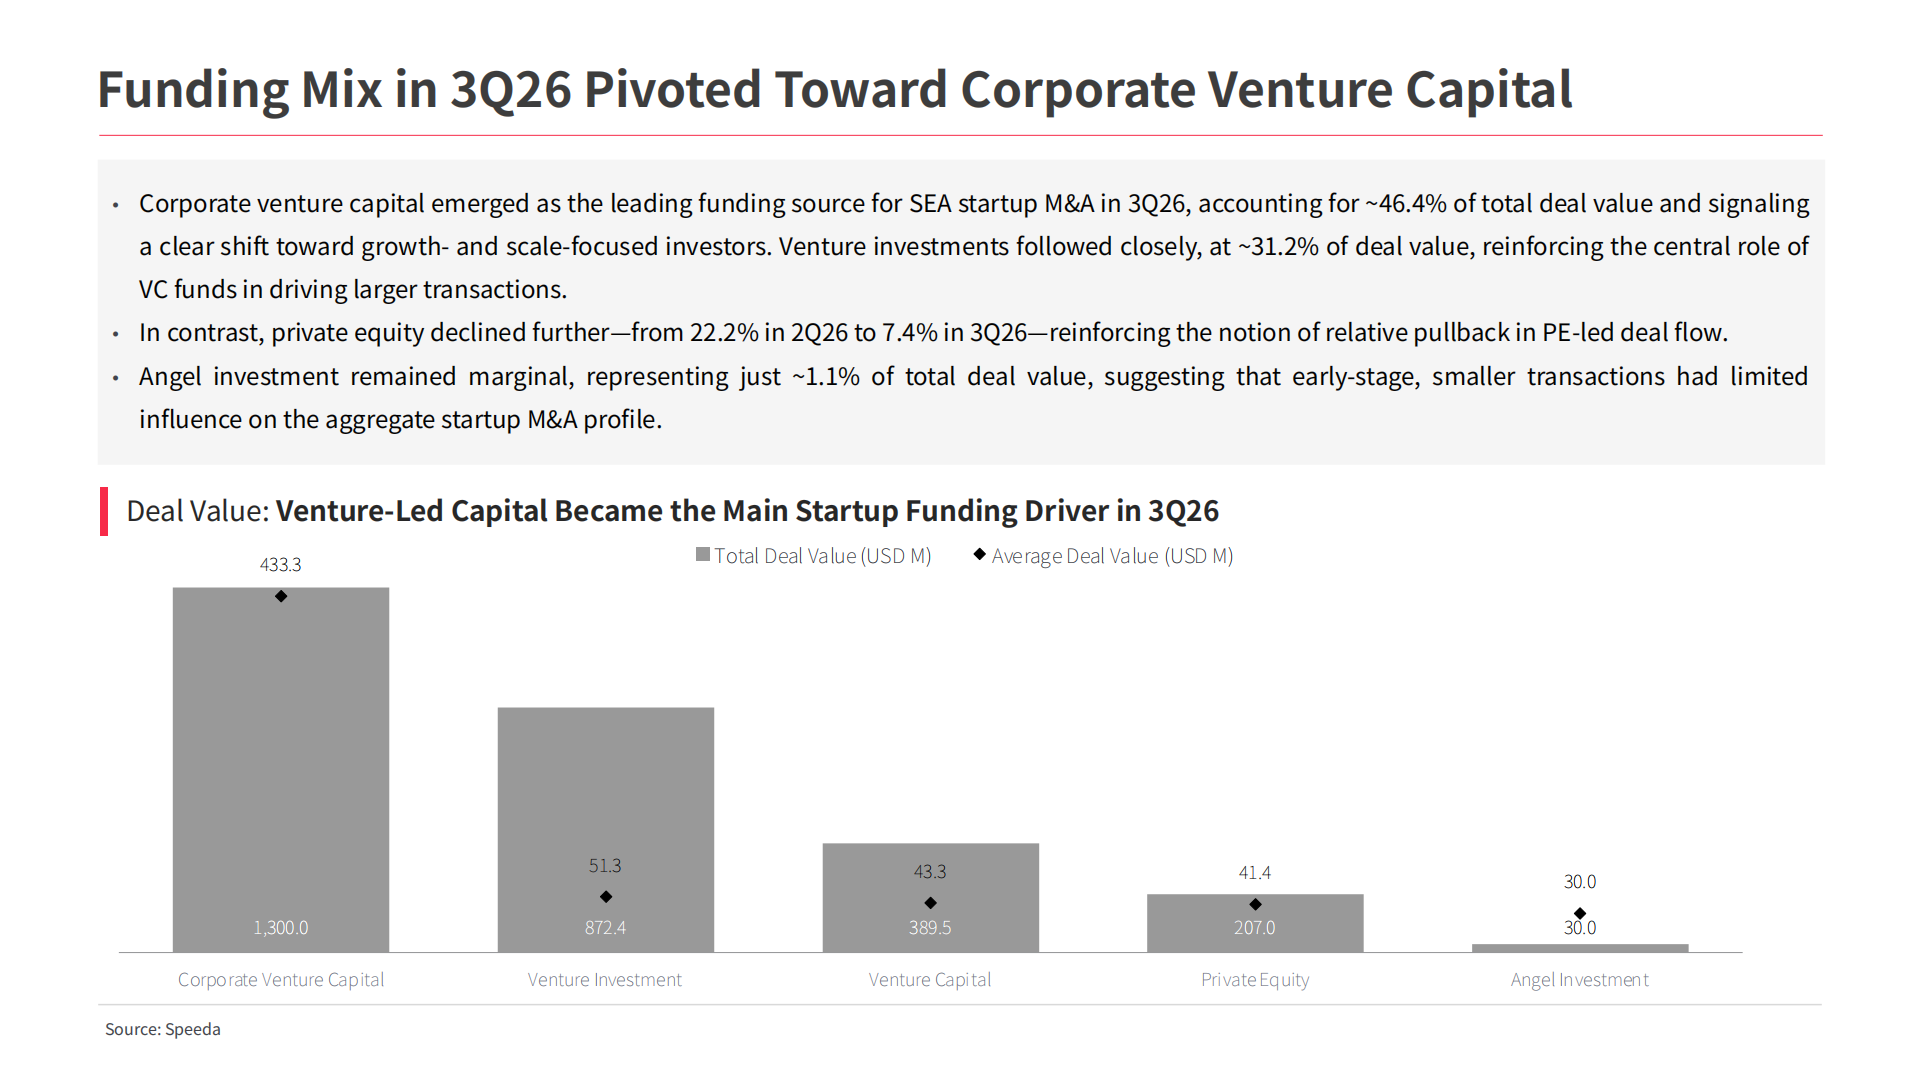
Startup deal value doubled QoQ in 3Q2026, but the source of capital shifted. Corporate venture capital became the leading funding source, at approximately 46.4% of startup deal value, followed by venture investment at around 31.2%. Private equity’s share fell from 22.2% in 2Q2026 to 7.4%.
The stage mix shifted as well. Series A rounds accounted for approximately 59.9% of startup deal value, while Series C and later rounds fell to 20.2% from around 54.5% in the previous quarter. This was driven largely by a few large rounds:
- Ant International raised approximately USD 1.2 billion in Series A financing, co-led by Ant Group and Alibaba Group.
- Volta AI, a Singapore-headquartered AI infrastructure startup, secured USD 300 million, co-led by Azora, Andreessen Horowitz and Altimeter Capital.
Singapore continued to dominate, accounting for approximately 98.2% of SEA startup deal value and around 82.9% of deal count.
The implication for investors: late-stage capital has become more selective, and corporate investors are taking a larger role. For VCs, that changes who sits across the table in later rounds. For PE firms, it raises the question of where growth-stage opportunities now sit.
What the full report adds: startup deal value by country and sector, the full funding mix and stage breakdown, and the key technology transactions of the quarter.
What these shifts mean for PE/VC investors
Speeda’s outlook expects SEA M&A volume to stay subdued, with large transactions continuing to support deal value. The US Federal Reserve’s 25 bps hike in September and Brent crude above USD 100 per barrel could keep financing costs elevated and prolong valuation gaps between buyers and sellers. In that environment, cash-rich strategic buyers and well-capitalised investors are likely to lead, with activity focused on AI-related infrastructure, selected property segments and renewable energy.
For PE and VC investors, the questions worth asking now are:
- Which regional strategic buyers are most active, and in which sectors?
- Where are valuations being set by the quarter’s largest transactions?
- How are corporate investors changing the competition for growth-stage deals?
- Which sectors are attracting capital despite tighter financing conditions?
What’s inside the full 3Q2026 SEA M&A Report?
Download the report for deeper analysis of:
SEA M&A trends
- Deal value and volume trends
- Large, medium and small transaction mix
- Inter-region and cross-border deal flows
- 4Q26 M&A outlook
Sector and country analysis
- Deal value by industry
- Median deal value and EV/EBITDA by sector
- Country-level deal activity
- Singapore’s M&A highlights and top deals
Transaction and dealmaker analysis
- Top 10 M&A transactions in Southeast Asia
- Target and buyer information
- Leading financial and legal advisors
Startup M&A
- Startup deal activity by country and sector
- Funding mix
- Funding stage
Looking beyond announced transactions?
For investors and advisors, understanding the M&A landscape often requires going beyond transaction announcements to research the private companies, industries and markets behind them.
Speeda provides largest coverage of private companies across Asia, helping deal professionals conduct company research, compare industries and investigate potential targets alongside broader market and M&A analysis.
Download the report to explore the data and transactions behind the quarter’s activity.
Thank you for your submission!
We will send an email with the download link to access the report shortly.

 spasia_lm@uzabase.com
Follow our Linkedin Page !

Our latest updates on
ASEAN reports and webinars are posted here.
- Recommended Content


Thank you for your submission!
We will send a follow-up email shortly. Please check your inbox.
spasia_lm@uzabase.com Follow our Linkedin Page !
Our latest updates on
ASEAN reports and webinars are posted here.